All News & Insights

The shelf is no longer the store 

Share

Understanding the modern shopper journey 

There was a time when retail strategy felt much simpler. 

Brands focused on getting on the shelf, gaining visibility, and securing as much distribution as possible. If you were in the right stores, with the right merchandising and the right support behind you, growth generally followed. 

For a long time, that playbook worked. 

Today, we’re operating in a fundamentally different environment. Consumers have changed how they make decisions. 

One of the questions I hear most often from brands is, “Where should we grow next?” 

My answer, “Let’s first understand how your shopper is actually shopping.” 

If we’re still building our growth strategies around yesterday’s shopper journey, we’re likely missing what’s happening right in front of us.  

Consumers are arriving with more decisions already made 

A few years ago, I was walking a store with a client and discussing shelf placement. We spent time reviewing assortment, competitive positioning, promotional strategy, and visibility opportunities. 

All important conversations. But afterward, it struck me that we weren’t discussing the shopper. 

Had they already seen the product online? Heard about it from a friend or creator they trust? Read reviews? Compared prices across retailers before walking through the door? 
 
The more I thought about it, the more apparent it became that the shelf was no longer where many decisions were being made. In many cases, it was where decisions were being confirmed.  

Consumers may still purchase at the shelf, but they’re increasingly deciding long before they get there. 

Physical and digital retail now complement each other so seamlessly that we may not even recognize how often we move between them. 

The purchase funnel evolved 

For years, our industry relied on a relatively straightforward view of consumer behavior: Build awareness. Drive consideration. Generate purchase. 

Today’s shopper rarely follows a straight path. 

They think about their needs. They think about solutions. And they think about trust. 

Consumers have more information than ever before, but what they’re really looking for is confidence: confidence they’re making the right choice, that a product delivers on its promise, and that a brand aligns with what matters to them. 

The brands earning that confidence are the ones creating meaningful connections long before the moment of purchase. 
 

Distribution creates opportunity, not demand 

Over the course of my career, I’ve seen one pattern repeat itself across brands at every stage of growth. 

Landing a major retailer is exciting. It creates energy throughout an organization and can feel like confirmation that the brand has arrived.  

There’s an understandable rush toward expansion. 

More retailers. More channels. More distribution. 

Growth becomes synonymous with reach. 

But I’ve also seen brands secure hard-won distribution and then struggle to generate the expected results. The presence was there. The consumer demand was not. 

That is because reach without relevance rarely creates sustainable growth. 

I’ve seen brands with relatively modest distribution outperform competitors with much larger footprints because they understood more deeply what problem they solved, how consumers discovered them, what motivated trial, and what created loyalty. 

They weren’t simply more available. They were more relevant. 

Being available matters. Being chosen matters more. 

Brands need to spend less time thinking about channels in isolation and more time understanding the moments that shape consumer decisions. 

What sparks discovery? 

What turns a first purchase into loyalty? 

Once those moments are understood, the path forward becomes much clearer. The goal is no longer to optimize a single shelf, campaign, or retailer. It is to create a connected experience across the shopper’s entire journey. 

The digital shelf, physical shelf, retail media, brand content, ratings and reviews, in-store merchandising execution, and word of mouth all play a role. Brands need to connect these touchpoints around the way shoppers actually discover, evaluate, purchase, and return to a product. 

To the consumer, that experience should feel seamless, even when it is anything but behind the scenes. 

This is where many growth strategies either accelerate or stall. 

Too often, teams operate in parallel rather than together. Shopper insights sit in one area, sales in another, marketing in another, and e-commerce somewhere else entirely. 

Yet consumers don’t experience brands that way. 

They see one brand. 

One promise. 

One experience. 

The companies creating sustainable growth are the ones aligning their organizations around how shoppers actually make decisions, not around how internal functions are structured.   

The best growth strategies start with curiosity 

When I think about the brands that consistently outperform, regardless of category, size, or channel, they share one trait. 

Curiosity. 

They’re endlessly curious about their consumers, and it shows up in the questions they ask. 

  • What motivates someone to try the product for the first time? 
  • What builds trust? 
  • What brings that person back? 
  • Where is the shopper experiencing friction? 
  • What is influencing behavior? 
  • What matters now that didn’t matter a year ago? 

Answering these questions requires brands to look beyond sales results and standard retail metrics. Sales data can tell us what happened. Shopper understanding helps explain why it happened. 

Both matter, but the “why” often reveals the greater opportunity. 

It can tell a brand: 

  • Why a product is gaining attention online but not converting in-store. 
  • Why trial is strong but repeat purchase is weak. 
  • There’s a disconnect between what the brand wants to communicate and what the shopper actually needs to hear. 

In a rapidly changing retail environment, that understanding is becoming increasingly valuable. 

Retail is becoming more human, not less 

There’s a lot of discussion today about technology, artificial intelligence, retail media, and data. 

Those topics are important. They’re changing how brands reach shoppers, how retailers engage them, and how consumers discover and evaluate products. 

But I sometimes wonder if we’re missing the bigger story. 

Technology is changing how shoppers make decisions. It isn’t changing why people buy. 

Despite all the change happening around retail, people still want the same things: products that solve real problems, brands they trust, and confidence they’re making the right choice for themselves or their families. 
At its core, retail remains a human business. 

The brands that remember that stay focused. They use technology to deepen consumer understanding, not replace it. They use data to ask better questions, not simply produce more reports. And they view every retail touchpoint as an opportunity to help the shopper make a more confident decision. 

The goal is not to be present everywhere just for the sake of being present. 

The goal is to be relevant when and where it matters. 

The longer I work in this industry, the more convinced I become that the future won’t automatically belong to the brands with the biggest presence. 

It will belong to the brands with the deepest understanding. 

The ones that listen more closely. 

The ones that stay curious longer. 

The ones that recognize consumer behavior as an opportunity rather than a disruption.  

The shelf still matters. It always will. 

But the shelf is no longer the store. 

It’s one stop along a journey that begins much earlier and extends far beyond the initial purchase. 

The real opportunity isn’t simply getting products into more places.  It’s earning a place in the consumer’s consideration, confidence, and ultimately, their trust. 

The brands that thrive won’t necessarily be the ones with the biggest footprint. They’ll be the ones with the clearest understanding of the people they serve. 

Today, we have more ways than ever to listen, learn, and connect with consumers. If we use those capabilities thoughtfully, we can create more than transactions. Because when brands take the time to understand what matters to consumers, where friction exists, and what shapes their decisions, they stop chasing growth and start creating it.

Follow Tamara on LinkedIn for her practical insight on scaling emerging brands in conventional retail. 
All News & Insights

Independent urban convenience: Reaching one of retail’s most fragmented channels 

Share

Urban c-stores represent one of retail’s most valuable, yet hard-to-reach channels.  

With thousands of independently owned locations across major markets, brands often struggle to introduce new products, drive trials, and build distribution. 

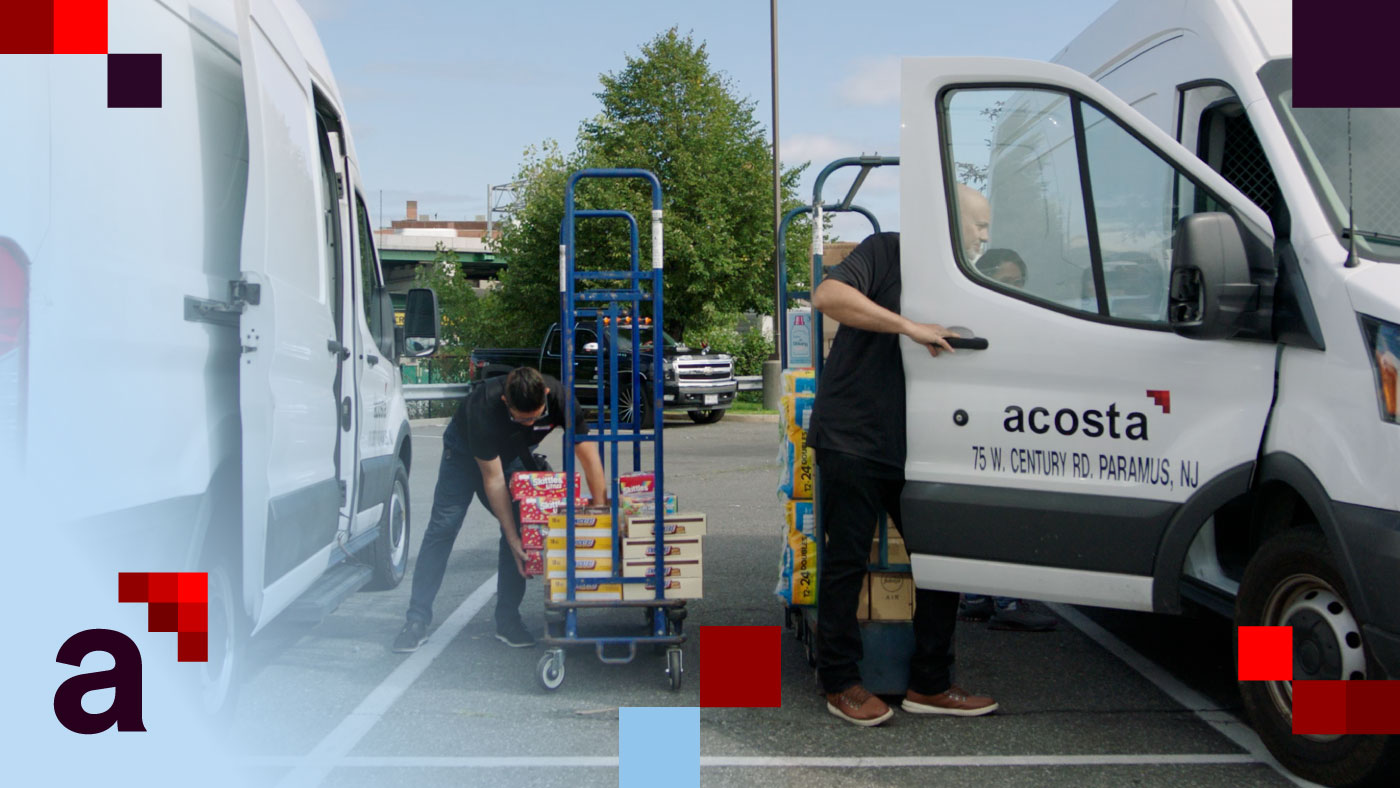
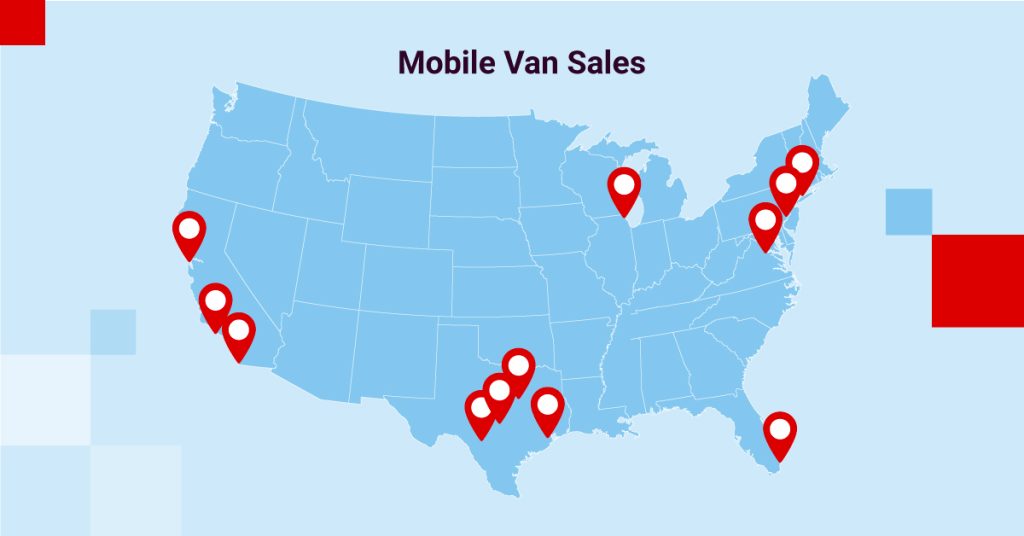
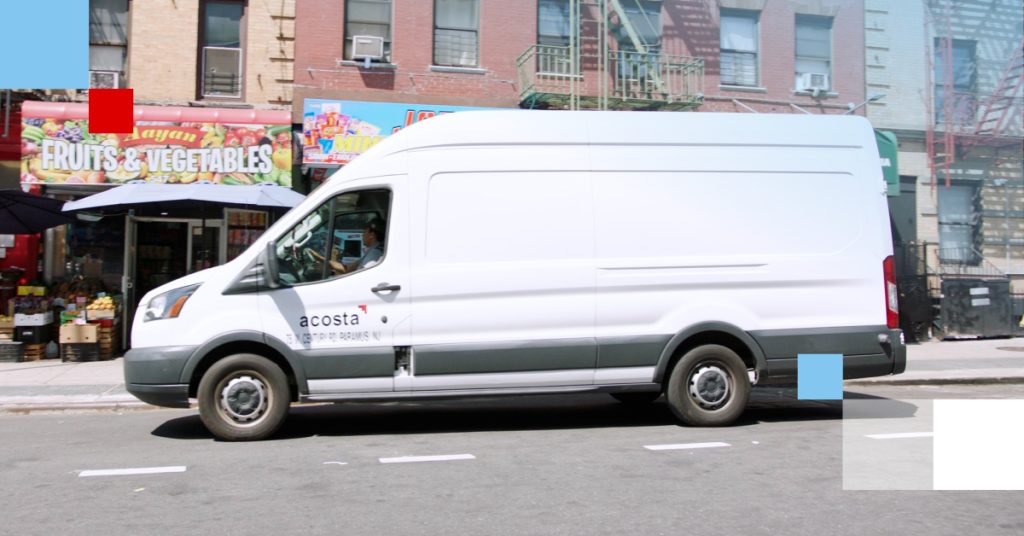
One approach that’s gaining traction is our urban van program. Today, the program reaches 24,000 independent convenience stores and bodegas across 12 of the nation’s largest urban markets. 

“When we go to urban, we focus on true urban,” explains Hobie Walker, SVP Small Format, Acosta. “Shoppers in these areas may not have the option of driving to traditional grocery or big box stores, or may choose not to use them, so we try to fill that need.” 

In busy metro areas, local is everything. SurgePays research found that 94% of shoppers in underserved urban communities feel their local stores are important, 59% visit their local independent retailer between one and six times weekly, and 46% have shopped at their local c-store or bodega for four or more years.  

Acosta Group’s 2025 Convenience Store Shopper Study found that 77% of shoppers living in markets served by the van program are making planned trips to their local c-store to purchase something they need, and 64% are making unplanned trips and purchasing impulse items, often on the way to or from work, an event, or a get-together.  

It’s a clear opportunity for c-store owners to build shopper loyalty by offering easy-to-shop snack assortments and ready-to-go options supported by promos and displays. 

Finding the right mix 

“Consumers are loyal to neighborhood stores,” says Walker. “So it’s our job to develop close relationships with owners, earning their trust by bringing in best-selling items that will drive sales and create a win for shoppers, retailers, and brands alike.” 

Across Acosta’s urban retail team, bilingual associates work with store owners and clerks, showcasing new items and sharing why they’re a good fit for customers. 

“We are true partners to retailers,” says Walker. “We educate owners on trends as we walk the stores with them, reviewing product mix and identifying whether they’re offering the right products, brands, and sizes.” And while Acosta doesn’t dictate pricing, account leads will let owners know if their prices vary significantly from the broader marketplace, helping them stay competitive. 

Acosta’s urban vans carry large manufacturer “power SKUs,” items known to perform strongly at a national level. They also carry “innovation items,” which often achieve an 80% distribution rate within eight weeks. Items are selected by the manufacturer, who works with Acosta to monitor sales throughout the year, making adjustments as needed. On occasion, regionality plays a role. For example, Big Red chewing gum is a staple in Texas, where cinnamon is a favorite.  

Vans come fully stocked and ready for retailers to purchase items. Once products are selected, Acosta reps help owners identify the best shelf location and layer in appropriate point-of-sale information and offers. If previously purchased items need replenishment and are available on the van, restocking happens immediately. As other items run low, retailers are reminded to go to their suppliers for restocking.  

Knowing what sells 

Understandably, owners are sometimes hesitant to take a chance on new items. But letting customers vote with their wallets is often all the proof they need. 

“Shoppers value name brands and product innovation, and they’re willing to pay to have that branded experience,” says Walker.   

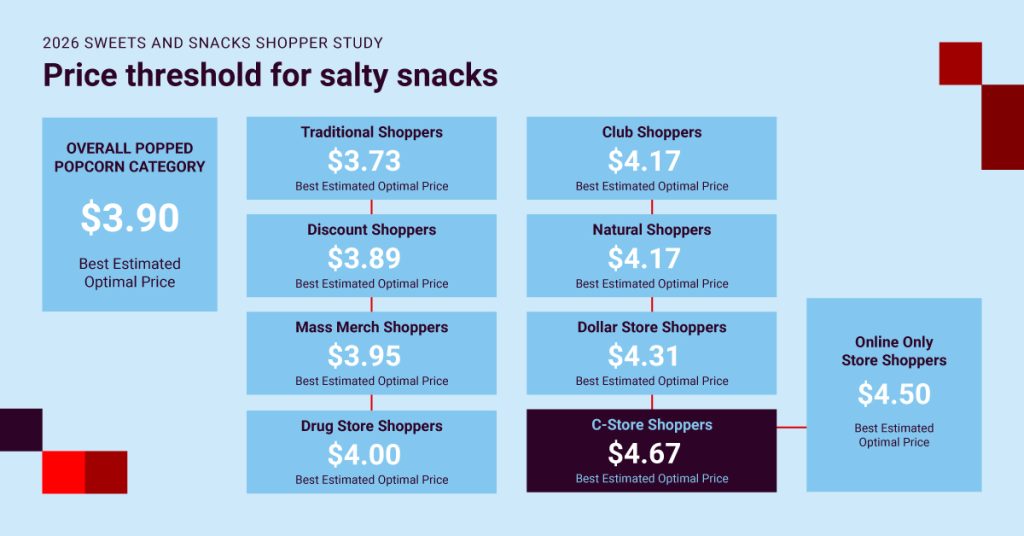
Acosta Group’s 2026 Sweets and Snacks Shopper Study supports this point, showing that, nationally, convenience shoppers have a higher pricing threshold for salty and sweet snacks than shoppers in the grocery, drug, club, and even discount or dollar channels.  

Acosta meets with its retail partners every eight weeks. The first question owners typically ask? “What do you have for me that’s new?” 

Making room for more brands 

Acosta’s urban van program has also become a distribution strategy for megabrands like P&G, Coca-Cola, Campbell’s Snacks, and Quest. Each has its own vans stocked with 50 to 60 products.   

“While we operate this program in cities where there is the highest density of independent convenience stores,” explains Walker, “we’re open to considering other markets based on client needs.” 

Earlier this year, Acosta opened the door for emerging brands to participate in the van program. By creating a consortium, Acosta introduced a cost-effective way for up to four manufacturers to collaborate, each offering up to a dozen hand-selected items to be featured on a small fleet of vans in designated markets. Initial participants have included Gummy Rush, Monarca Authentic Snacks, and Zynga, and early results have been strong.   

Investing in the field 

To ensure continued success, Acosta provides rigorous training to its urban van team. After a formal onboarding period, sales representatives go into the field to work with owners, with a district manager there to observe and coach. 
 
“When we leave a store visit, we need to know that the owner and sales associates understand the products they’ve selected and that items have been merchandised to their greatest advantage,” says Walker. “We want them to be positioned for success from day one.”  

C-stores represent a vibrant and ever-evolving retail environment. Innovative programs that help independent retailers earn more business are a win for brands, for owners, and for millions of urban shoppers. 

All News & Insights

Fresh foods: The growth engine driving the future of all outlet sales

Share

Growth often starts when we step outside our comfort zones. Writing a blog is new for me, but I’ve always believed that learning and growth come from embracing new challenges. So, here goes. 

Today, fresh foods sit at the center of the consumer experience and remain one of the strongest drivers of differentiation, loyalty, and growth across edible outlets. As I connect with consumers, operators, brand owners, and industry leaders, one theme consistently emerges: the future of fresh will be shaped by quality, convenience, omnichannel engagement, artificial intelligence, and the ability to make fresh foods a meaningful part of consumers’ lifestyles. 

Quality is still the foundation

One of the best pieces of advice I ever received was simple: good food sells. 

No matter how advanced technology becomes or how seamless the digital experience may be, quality must remain at the heart of every fresh food strategy. If the food fails to meet expectations, nothing else matters. 

We’ve all experienced it: one disappointing produce purchase can influence future shopping decisions, while an exceptional meal or fresh food experience builds trust, loyalty, and repeat purchases. 
 
The recent Cyclospora outbreak has brought renewed attention to food safety. My thoughts are with those affected, and it will be important to watch how consumer perceptions evolve — not only to the specific products and brands involved, but to the broader produce category, particularly leafy greens. Historically, food safety incidents can influence shopper confidence beyond the brands directly impacted, creating ripple effects across an entire category. It’s a reminder that trust, transparency, and quality remain essential throughout the fresh food supply chain. Quality builds trust, and trust builds loyalty. 

Convenience continues to shape consumer behavior

Consumers are busier than ever, and fresh foods increasingly need to fit seamlessly into their lifestyles. 

Prepared foods, meal kits, grab-and-go offerings, and restaurant-quality solutions continue to gain momentum as consumers seek convenience without sacrificing quality. 

Consumers don’t think in channels. They think in meal occasions. Their goal is simple: finding the right food solution at the right time through the most convenient experience possible. 

For operators and brands, this creates opportunities to capture a larger share of meal occasions by delivering fresh solutions that simplify everyday life. 

Consumers expect a seamless experience

Fresh foods have become one of the ultimate tests of a successful omnichannel strategy. Today’s consumers may browse an app, review loyalty offers, order online, schedule pickup, or choose delivery — all before ever stepping into a store or restaurant. Regardless of how they engage, they expect a consistent, high-quality experience throughout the entire journey.  

And quite simply, moving fresh products seamlessly across channels is more complex than managing shelf-stable goods. But if growth were easy, the journey wouldn’t be nearly as rewarding. 

A simple look at my own family reinforces this trend. 

Just last week, my wife, our 18-year-old son, our 14-year-old daughter, and I purchased food from club stores, grocery stores, mass retailers, coffee shops, fast-casual restaurants, a quick-service restaurant, a food truck, and yes, several ice cream shops (my daughter and I have a particular appreciation for ice cream). We also enjoyed several meals at home and likely a few other food occasions I’ve already forgotten. Some decisions were made on our phones before we ever left the house, while others happened in the moment. 

My son recently started a part-time job delivering orders for a food delivery app as he saves for college spending money. The stories he brings home have been both entertaining and insightful. They reinforce a growing reality: consumers expect food on their terms wherever and whenever they want it. 

Today’s shoppers don’t distinguish between digital and physical experiences. Whether they’re ordering from a phone, shopping in-store, grabbing a meal from a food truck, or having dinner delivered, their decision-making is driven by convenience and accessibility. 

The question for brands is simple: Are you present wherever consumers choose to shop, dine, order, or discover food? If not, there is a significant opportunity to expand your reach, strengthen engagement, and grow your business. 

AI is reshaping fresh

Artificial intelligence is also becoming an increasingly important part of the food purchasing process. From recipe inspiration and meal planning to personalized promotions and product discovery, AI is influencing decisions long before consumers make a purchase. A recent Numerator survey found that 51% of shoppers have used or are likely to use AI when engaging with restaurants, while 48% reported the same for grocery shopping. My belief is those numbers will continue to climb rapidly in the years ahead. 

The operators and brand owners that successfully combine fresh food expertise, omnichannel excellence, and AI-driven insights will be best positioned to build loyalty, deepen consumer engagement, and drive sustainable growth. 

National brands and operator brands both win

Another trend shaping fresh foods is the continued growth of both national brands and operator brands across virtually every food outlet. In a recent Acosta Group shopper study focused on fresh foods across retail, 82% of shoppers indicated that it is important for the fresh department to feature well-known national brands. 

National brands bring innovation, consumer trust, awareness, marketing investment, and category leadership. They often introduce new products, trends, and solutions that drive shopper engagement and category growth. 

At the same time, today’s operator brands have evolved far beyond the value-focused alternatives of the past, delivering quality, innovation, differentiation, and strong value.  

The most successful operators recognize this isn’t an either-or decision. They use both to create a balanced assortment that maximizes choice, quality, and shopper appeal. 

In the end, consumers win. They benefit from trusted brands they know and love, alongside compelling operator-brand offerings that continue to raise the bar across the fresh food experience. 

Fresh foods are about more than food 

Fresh foods are deeply connected to how we live. They bring people together, support health and wellness, and play an important role in many of life’s everyday moments. 

Think about a meaningful memory where fresh food played a role. For me, it was my son’s recent high school graduation party. We were surrounded by family, friends, and plenty of great food including a local favorite called a Garbage Plate (ask me about it sometime). 

What I remember most isn’t the food itself but celebrating my son and sharing that milestone with the people who helped shape him. 

Chances are one of your favorite memories also includes fresh food, too. A holiday meal, backyard barbecue, family gathering, or celebration with friends. That’s the power of fresh. It nourishes us physically while connecting us emotionally.

Looking ahead

The future of fresh belongs to organizations that successfully combine: 

  • Exceptional product quality 
  • Convenience and meal solutions 
  • Omnichannel execution 
  • AI-enabled insights and personalization 
  • Balanced national brand and operator-brand strategies 
  • Fresh foods as an integral part of consumers’ lifestyles 

Fresh remains one of the primary reasons consumers choose one operator or brand over another. The winners of tomorrow will make fresh easy to discover, purchase, trust, and personalize through AI-enabled experiences. 

Fresh foods are a strategic growth engine across edible outlets. The operators and brands that embrace this evolution will not only gain market share but also build deeper, longer-lasting consumer relationships. 

I hope these thoughts spark conversation, and I welcome the opportunity to learn from others across our industry. One lesson I have learned throughout my career is that some of the best insights come from shared experiences and diverse perspectives. 

All News & Insights

Acosta Opens New Growth Channel for Manufacturers Through Salvatori-Scott Partnership

Share

National retail scale meets specialized independent pharmacy expertise to accelerate health and wellness expansion 

JACKSONVILLE, Fla. — As health and wellness brands look beyond traditional retail for growth, the independent drug channel is emerging as an increasingly important opportunity. To help manufacturers capitalize on that shift, Acosta has partnered with Salvatori-Scott Inc. (SSI), combining national retail capabilities with specialized expertise in independent pharmacy and health care channels. 

For manufacturers, the result is a more connected way to reach one of retail’s most specialized markets. The partnership brings together national sales coverage, retail execution, analytics and omnichannel capabilities with decades of independent drug expertise, helping brands strengthen distribution while expanding opportunities across managed care organizations, Medicare Advantage programs, group purchasing organizations, hospitals and long-term care providers.

“Manufacturers have been asking for a simpler way to reach the independent drug channel without sacrificing the scale and capabilities they need across the rest of retail,” said Denise Wellander, senior vice president of Drug and Value at Acosta. “Rather than spending years building those capabilities ourselves, we chose to partner with the company that has already earned the trust and relationships throughout this space. Together, we’re making it easier for clients to pursue growth opportunities that were previously much harder to access.” 

The partnership reflects Acosta’s continued investment in strategic growth areas where retail and health care increasingly intersect. It also creates new opportunities for SSI to extend its specialized expertise to manufacturers seeking broader, multi-channel solutions backed by Acosta’s national scale.

Where retail meets health   

Independent pharmacies have long played a unique role in the health care ecosystem, serving as both neighborhood retailers and trusted health care destinations. Beyond prescription medications, they influence purchasing decisions across vitamins, nutritional supplements, over-the-counter medicines, personal care products and other wellness categories. Yet the channel has traditionally required specialized relationships and expertise that differ from other areas of retail. 

SSI has spent decades building those relationships throughout independent pharmacy, wholesale distribution and health organizations. Acosta complements those capabilities with deep category expertise, national customer relationships, analytics, omnichannel commerce and retail execution, creating a more complete solution for manufacturers looking to grow across multiple channels. 

“Our clients rely on us for specialized expertise and deep relationships within the independent drug marketplace,” said Dan Briggs, president of Salvatori-Scott Inc. “Partnering with Acosta allows us to build on that foundation while giving manufacturers access to broader capabilities across grocery, mass, value and other retail channels. Together, we’re creating new opportunities for clients without losing the specialized focus that has always defined our business.” 

As consumers increasingly shop for health and wellness products across multiple retail and health care settings, manufacturers need partners that understand both environments. The Acosta-SSI partnership brings those capabilities together, helping brands navigate a more connected marketplace while creating new opportunities for growth. 

The companies have already begun supporting shared clients and identifying new opportunities to expand distribution and strengthen market presence. Acosta and SSI will showcase their combined capabilities during the upcoming NACDS Total Store Expo, where they will meet jointly with manufacturers and customers to discuss opportunities across independent pharmacy and the broader health care marketplace.

All News & Insights

Growth starts with trust, not trends

woman looking at item in retail aisle

Share

There’s no shortage of innovation in health, beauty, and nutrition. Walk any retail aisle or scroll any digital shelf, and you’ll see it: more claims, more functionality, and more “better-for-you” positioning than ever. 

But innovation alone is not what’s driving growth. In many cases, it’s creating noise. 

Winning brands and retailers are not the ones chasing every emerging trend. They are stepping back, understanding what has fundamentally changed about the consumer, and building strategies around that reality. 

Because the biggest shift is not about protein, hydration, or clean ingredients on their own. It is about trust. 

A more intentional consumer 

The modern consumer is more informed and more skeptical than ever. 

Coming out of the pandemic, people didn’t mindlessly return to old habits. They re-evaluated them. Health became more than a category. It became a decision-making filter across food, personal care, and household products. 

That shift has reshaped expectations: 

  • Ingredient transparency is now a baseline (not a differentiator) 
  • Value is not defined solely by price  
  • Brand loyalty is earned through credibility, not familiarity  

Consumers are not just asking “Does this work?” They’re asking, “Do I trust this?” and “Is this right for me and my family?” 

That’s a meaningful change, and it requires a different response from both brands and retailers. 

When trends turn into noise 

Protein is a clear example of how quickly a trend can become diluted. 

What started as a functional category aimed at specific consumer needs has expanded into near ubiquity. Protein now appears across snacks, cereals, and beverages. 

That growth reflects real consumer demand, but it also raises an important question: are we solving a need, or following a trend? 

Not every product benefits from added functionality. In many cases, adding more creates confusion rather than value.  

This pattern extends beyond protein. Hydration, functional ingredients, and even wellness claims are being applied broadly, often without a clear role in the consumer’s life. 

The brands that stand out are not adding features indiscriminately. They’re making deliberate choices about where innovation truly matters. 

Experience is becoming a differentiator 

At the same time, products are becoming more experiential. 

This is especially evident in beauty and home care, where product design is becoming more layered, sensory, and emotionally resonant. Fragrance is a powerful example. What was once largely functional has evolved into a way for consumers to express mood, identity, and personal preference. 
 
Consumers increasingly want products that do more than perform. They want products that feel personal and turn everyday routines into small moments of comfort, enjoyment, and escape. That expectation accelerated during the pandemic and has not gone away. 

For brands, this raises the bar. Experience cannot be treated as a decorative layer or a final touch. It needs to be built into the product, the sensory cues, and the brand story from the start. 

Overlooked opportunities in holistic health 

While some trends have been overextended, others have not been fully developed. 

Holistic health is one of them. 

There was a period when categories like vitamins, supplements, and natural wellness were central to the conversation. Then the focus shifted toward more immediate, functional benefits like protein and hydration. 

But the underlying need didn’t go away. 

Consumers are still looking for solutions that support total well-being, including gut health, mental wellness, sleep, and immunity. What’s missing is cohesion and credibility in how those benefits are delivered. 

This is where meaningful innovation lives. Not in incremental plug-and-play product extensions, but in solutions built for the complexity of human needs and grounded in earned trust. 

Alignment between retailers and brands 

One of the biggest barriers to growth is lack of alignment. 

Retailers are focused on engagement, basket size, and category performance. Brands are focused on differentiation and share growth. 

Both perspectives are valid, but they do not always connect. 

Ingredient transparency is a good example of the gap. Consumers are actively seeking products that meet specific criteria, whether that’s aluminum-free or simplified ingredients. Yet those products can still be difficult to find in-store. 

When brands try to communicate everything through packaging, it overwhelms. When retailers don’t create clear pathways, the burden shifts to the consumer. 

The key is collaboration. Brands need to clearly define their value. Retailers need to make those products easier to find and shop. 

Better alignment helps retailers become destinations, and brands become easier to choose. 

Digital execution as growth lever 

Digital remains one of the most underutilized opportunities in health, beauty, and general merchandise categories. 

Despite significant growth in e-commerce, many brands still treat digital as secondary. Product pages are often sparse, offering minimal imagery and little context. 

In a digital environment, the product has to work harder. Consumers cannot see, touch, or test it. Brands must clearly communicate what the product is, how it fits into a routine, and why it matters. 

Strong digital execution includes: 

  • Clear and compelling imagery  
  • Context for how the product is used  
  • Simple, visual communication of key benefits 

Changes can be implemented quickly and scaled efficiently. But only when digital content is treated as a priority. 

What comes next 

The next phase of HBC and non-foods growth will not be defined by a single trend. 

It will be defined by how well brands and retailers respond to a more intentional, more discerning consumer. 

That means: 

  • Building trust through transparency and consistency  
  • Prioritizing meaningful innovation over incremental additions  
  • Creating products that deliver both function and experience  
  • Making “better‑for‑you” easier to discover 
  • Elevating digital execution to meet expectations  

These categories are deeply personal. They shape daily routines and long-term well‑being. 

The opportunity is significant. But success will require discipline and clarity on what truly matters. 

Follow Megan on LinkedIn for her practical insight on scaling your brand in retail.

All News & Insights

Shoppers are prioritizing clean and affordable

hands holding two jars of food

Share

Eating well used to come with an assumption: it’s going to cost more. 

That tradeoff is now under pressure. 

Shoppers are still prioritizing clean ingredients, transparency, and products that support their overall well-being. But persistent cost pressures are forcing more scrutiny with every purchase. The result is a more calculated approach to the basket, where every item has to justify both its nutritional value and price. 

This shift is reshaping expectations across the natural channel. It’s no longer enough for products to be better-for-you. They also have to prove they’re worth it, quickly. 

Health expectations are holding. Spending isn’t.

Demand for better-for-you products has not softened. If anything, it has become more intentional. 

Shoppers are paying closer attention to ingredients, seeking out products that align with specific needs, whether it’s digestive health, dietary restrictions, or broader wellness goals. Food is increasingly viewed as a long-term investment, not a short-term purchase. 

What has changed is how those decisions are made. 

Cost pressures are reaching a broader set of consumers, including those who were previously less sensitive to price. That’s forcing tradeoffs, but not necessarily away from health. Instead, shoppers are becoming more selective, looking for ways to maintain their standards while managing spend. 

For brands, that shift raises the bar. Products are no longer evaluated in isolation. They’re compared with expectations around both performance and price.

The affordability reset 

For years, natural and organic products have carried a price premium. That perception is starting to shift. 

Shoppers are recognizing that eating well doesn’t always require a major boost in spend, especially as assortments expand and pricing becomes more competitive. At the same time, they’re becoming more deliberate about where they’re willing to pay more and where they’re not. 

Private label is accelerating this, increasingly setting the baseline for value as shoppers look for cost-effective options that still meet quality expectations. For branded products, the question is no longer whether a product is healthier. It’s whether the difference justifies the price. 

Premium is earned, not assumed. 

Clarity is driving conversion 

Clarity has become one of the most powerful levers at shelf. 

Shoppers are not willing to decode complex labels or compare dense ingredient lists. They’re making faster decisions and relying on signals that are easy to understand at a glance. 

Products that communicate effectively, through simplified ingredients and straightforward messaging, are gaining traction. In many cases, they’re outperforming more established competitors, even when priced higher. 

The difference is not always the product itself. It’s how quickly the value is understood. 

Merchandising is critical here, and brands have a role in enabling it. Clear value signage, curated assortments, and simple meal solutions help shoppers connect health and affordability in real time. 

When executed well, these tactics make it easier to feel confident in the decision.

Trust still favors natural 

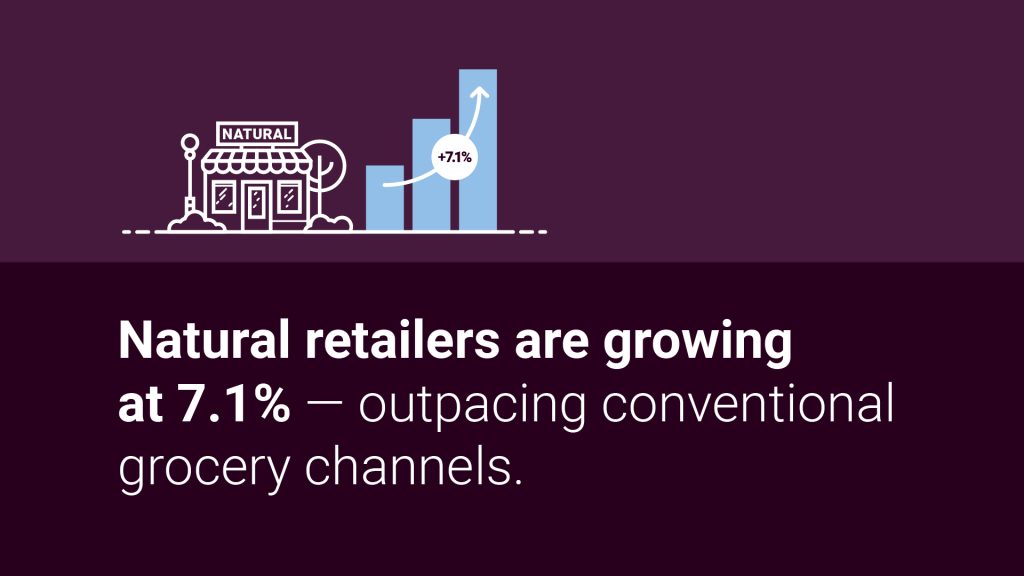
Natural retailers still benefit from built-in trust. 

Shoppers walk in with the expectation that products meet a certain standard. That reduces the need for deep research and speeds decision-making. It also reinforces why the channel continues to perform well relative to more conventional formats. The experience is more focused, more navigable, and more aligned with shopper intent. 

For brands, that trust creates both an advantage and a constraint. Products that meet the standard can convert faster, but those that fall short on clarity or credibility are quickly filtered out. 

Conventional retailers are making progress, particularly as better-for-you assortments expand. But there’s still an opportunity to improve how those products are surfaced and explained. When healthier options are priced at a premium, context matters. Without it, price becomes the deciding factor.  

Digital is raising the bar for transparency 

The role of digital in this space is growing quickly. 

Tools like barcode scanning apps are making it easier for shoppers to evaluate products instantly, translating ingredient lists into digestible information. Shoppers now expect this information to be accessible across the board. 
 
Brands, in partnership with retailers, can build on this through digital merchandising, targeted promotions, and online platforms that reinforce product attributes. Some categories lend themselves to this type of engagement more than others, but the broader trend is clear. 
 
Shoppers expect access to information. The easier it is to find and understand, the more likely it is to influence the purchase. Brands that invest in complete product data, attribute tagging, and digital discoverability are better positioned to benefit from these behaviors. 

Pricing strategy is becoming more intentional 

Affordability does not mean racing to the bottom. 

A more effective approach is emerging, one that maintains a clear relationship between private label and branded products. Private label anchors value, while brands justify a premium through differentiation. 

This balance keeps shoppers in the category rather than trading out entirely. It also reinforces that value is about more than cost. It’s about what the product delivers in return. 

Lean too heavily on price, and differentiation disappears. Lean too far into premium, and relevance declines.

Where brands can win now 

The convergence of health and affordability is not a short-term shift. It reflects a more disciplined, more informed shopper. 

Consumers are not lowering their expectations. They want products that support their health, align with their values, and make sense for their budgets. And they expect those benefits to be apparent from the start. 

For brands, the path forward is practical.  

  • Make better-for-you benefits easier to understand. 
  • Communicate value quickly and credibly.  
  • Structure pricing to maintain a clear role alongside private label.  
  • Remove friction wherever possible, both in-store and online. 

Eating well doesn’t always have to cost more. Proving that to shoppers requires more deliberate execution than ever before. 


All News & Insights

Natural is no longer just a channel — it’s a consumer expectation 

Share

For a long time, our industry has treated “natural” as a channel. 
A defined space. 
A separate aisle. 
A different kind of shopper. 

That framing no longer holds. 

What we’re seeing today isn’t the growth of a niche, it’s the evolution of consumer expectation. Clean ingredients, transparency, and purpose-driven brands are no longer confined to specialty retail. They are influencing how shoppers evaluate products everywhere, from natural and specialty stores to mass and traditional grocers. 

The implication is simple, but significant: If natural is still being approached as a channel strategy, brands risk missing what today’s consumer truly expects. 

From niche channel to consumer standard

During my three decades in CPG, including nearly 20 years at The Clorox Company, I had the opportunity to help integrate a vitamin and supplement business into a large-scale organization.  This experience fundamentally changed how I view the natural consumer. 

That work required a deep understanding of a shopper who was highly engaged, highly informed, and deeply intentional about what they were putting into their bodies. What stood out then and continues to stand out now is that this consumer doesn’t see “natural” as a category. They see it as the standard and way of life.  

That mindset has only accelerated. Shoppers have access to more information than ever before, and they’re using it. Labels, sourcing practices, ingredient transparency, and brand values are no longer secondary considerations, they’re central to the purchase decision. 

Consumers may begin their journey in a natural retailer, but they now expect to find those same standards wherever they shop. The line between channels isn’t just blurring. In many ways, it’s disappearing altogether. 

The opportunity — and the tension 

This shift creates real opportunity for brands, but it also exposes some common missteps, particularly as emerging brands scale.  
 
One of the most frequent challenges I see is the push for distribution without a clear strategy behind it. 
 
Growth creates momentum, and momentum creates urgency. But not all distribution is productive distribution. Expanding too quickly, without strong velocity, operational readiness, or a clear brand foundation, can dilute both impact and identity.  

The brands that succeed tend to be more disciplined. They build credibility in the right places, establish strong performance, and expand with intention. Simply put, they’re willing to go slow in order to grow sustainably. 
 
At the same time, the operating environment has become more complex. Many brands rely on multiple broker partners across regions and channels. While this can create reach, it can also fragment execution. Messaging becomes inconsistent. Storytelling loses clarity. Over time, the brand itself can feel diluted in the market. 
 
In the natural space especially, consistency matters. The consumer isn’t just buying a product, they’re buying into a belief system, a story, and a promise. When that promise feels unclear, trust erodes. 

When innovation outpaces clarity 

Layered onto all of this is a shopper navigating an increasingly crowded and noisy marketplace. 

Industry events like Natural Products Expo West highlight just how fast innovation is moving. Functional beverages, protein fortification, fiber-forward formulations. Creativity is undeniable. 

But innovation doesn’t always equal clarity. 

Adding a trending ingredient doesn’t automatically make a product better for the consumer. In some cases, it adds confusion. The responsibility of our industry isn’t simply to innovate, but to ensure that innovation is meaningful, credible, and aligned with why consumers came to this space in the first place: their health. 

This is where purpose-driven brands hold an advantage. If they protect it. 

Many of the strongest brands in natural were built to solve a real problem. That origin matters. It’s what establishes trust and authenticity. As brands scale, the challenge becomes maintaining that clarity of purpose. 

Every decision, from distribution to merchandising to messaging, should come back to a simple question: What problem are we solving for the consumer? 

When that remains clear, growth is more sustainable. When it doesn’t, the brand risks becoming just another option on the shelf. 

What this shift requires of brands 

Natural isn’t going away. It’s becoming embedded in how consumers define quality across every retail environment. 

The opportunity for brands and for the industry is not just to participate in this shift, but to lead it with focus and discipline. 

That means: 

  • Being intentional about where and how you scale 
  • Maintaining consistency in your story and execution 
  • Staying deeply grounded in the needs of the consumer 

Because this isn’t about a channel. 

It’s about earning trust in a more informed, more selective, and more empowered consumer landscape. 

What the strongest natural brands get right

For me, this moment feels less like a trend and more like a quiet reset. Consumers are telling us clearly that they expect more. More transparency. More intention. More respect for what they put into their bodies and why it matters. 
 
Natural isn’t about where a product sits on the shelf anymore. It’s about the standards behind it. The brands that will endure are the ones that listen closely, stay grounded in their purpose, protect their standards, and resist the urge to chase growth at the expense of trust. 

If there’s one takeaway, it’s this: meeting today’s consumer doesn’t require reinventing who you are. It requires the discipline to stay clear about what you stand for. And when that clarity is present, the rest tends to follow. 

Follow Tamara on LinkedIn for her practical insight on scaling natural and emerging brands in conventional retail.